Damage documentation
Roof insurance claim help in Long Beach, CA
Wind tore up part of your roof or a branch came down on it, and now you need to file with your insurance company. You need clear proof of what happened and what the repair will take.
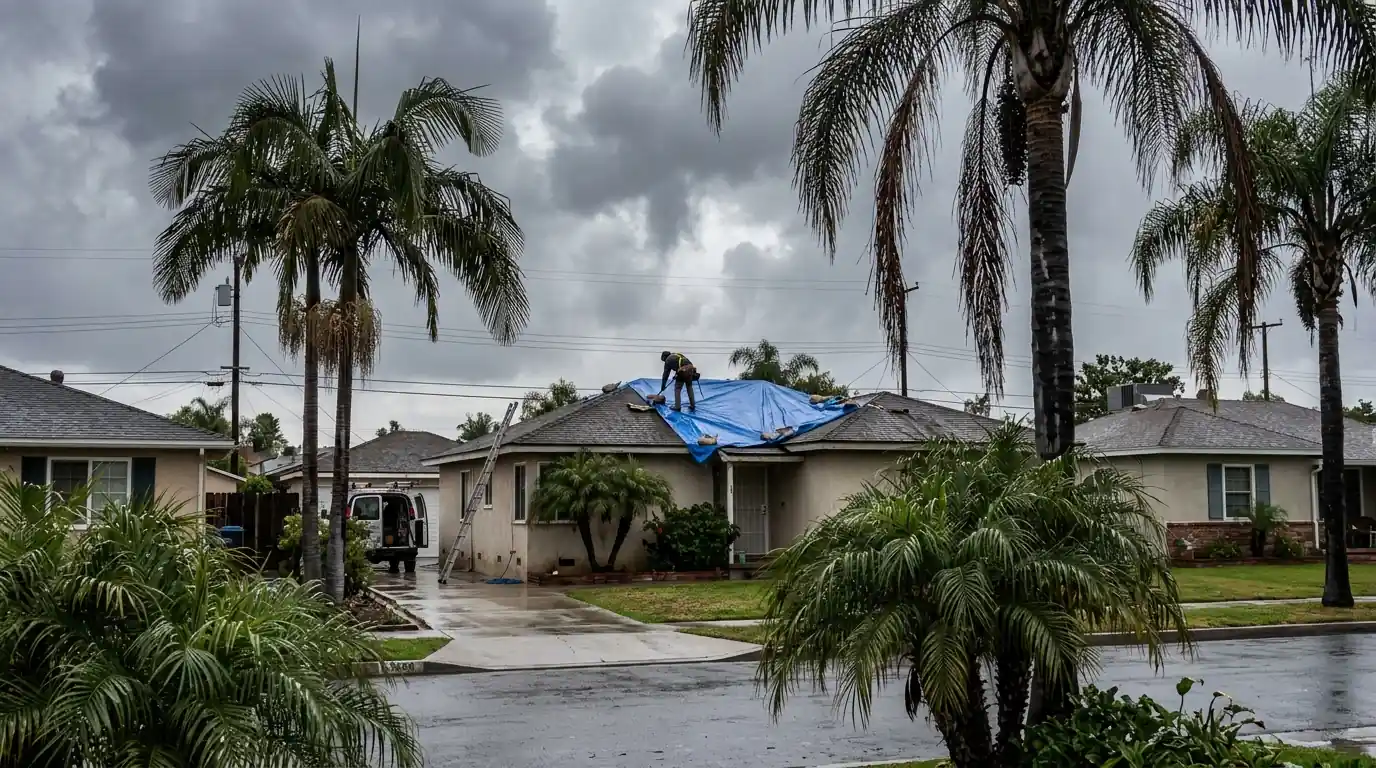
Roof insurance claim help means we inspect the damage, document it with photos and measurements, and write a repair estimate you can give your own insurer. It is useful after windstorms, fallen trees or limbs, and sudden leaks during heavy rain. Typical pricing is inspection and documentation $185 to $385, and repair work is priced separately once we know the scope.
After a storm, most homeowners have two jobs at once: keep the house dry and figure out whether insurance will help. The second part goes better when the damage is documented by someone who knows roofs. An adjuster will look at your roof, but they look at many roofs in a week, and a clear file from your own roofer helps them see exactly what happened to yours.
We inspect the damage, photograph it from wide shots down to close details, measure the affected area and write a repair estimate in plain terms. We also tarp or temporarily seal the roof if it is open to weather, because most policies expect you to prevent further damage. What we do not do is promise an outcome. Coverage decisions belong to your insurer and depend on your policy.
What we document for your insurer
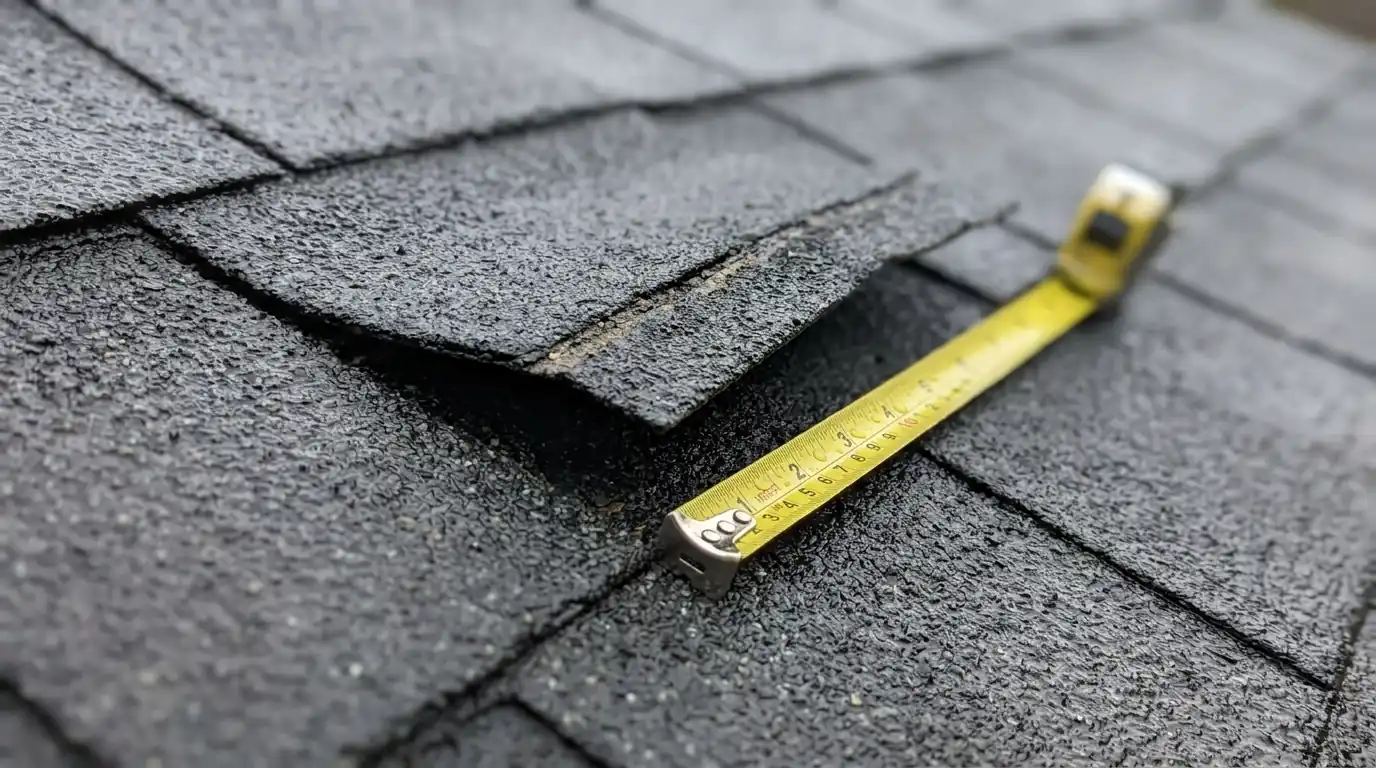
Insurers want to know what was damaged, when, by what, and what it will cost to fix. Our documentation answers those questions with evidence. We photograph the whole roof so the damaged area can be placed in context, then take close photos of each broken tile, creased shingle, torn membrane or bent flashing. Inside, we photograph any staining or wet decking from the attic.
We note the likely cause based on what we see: lifted and creased shingle tabs from wind, a gouge and crushed tile from a falling limb, a section of flat roof peeled back at an edge. We also note what we see that is not storm related, because an honest file is more useful than an inflated one.
- Wide and close photos of every damaged area
- Roof measurements and the size of the affected section
- Notes on likely cause and the date of the event
- Attic photos of water entry and wet materials
- A written repair estimate with materials and labor
Sudden damage versus wear and age
Most homeowner policies are written to cover sudden, accidental damage, and many exclude normal wear, age and lack of maintenance. That difference matters on a roof. Shingles blown off in a single Santa Ana wind event look different from shingles that have been cracking and shedding granules for years. Tile broken by a falling branch looks different from tile slipped out of place as old fasteners rusted.
We describe what we see as it is. If the damage looks storm related, we say so and show why. If parts of the roof show long-term wear, we note that as well. That keeps the file credible, and it helps you understand where you stand before the adjuster visit rather than after.
Meeting the adjuster and keeping the house dry
If you want us there, we can meet your insurance adjuster at the house and walk them through what we documented. We point out the damage, answer questions about how the roof is built and how the repair would be done, and explain our estimate. We are your roofer, not a public adjuster. We do not negotiate your settlement or represent you in the claim, and you stay in charge of every conversation with your insurer.
While the claim moves forward, the roof still has to keep water out. If there is an opening, we tarp it and secure the tarp against wind. Keep the receipt for that work, since temporary protection is often part of what a claim considers.
When to call about roof insurance claim help
Shingles blown off
Missing shingles or creased tabs after strong winds are a classic wind damage pattern worth documenting right away.
Tree limb on the roof
A fallen branch can crack tile, puncture decking or tear flashing. Photos before removal help show what happened.
Sudden ceiling leak
Water coming through during a storm needs a tarp first and documentation second. We can handle both on one visit.
Ridge tiles displaced
Wind and minor earthquakes can shift ridge and hip tiles. Loose pieces should be checked and recorded.
Flat roof edge peeled
Strong gusts can lift an edge of a flat or low-slope membrane and fold it back, opening the roof underneath.
Adjuster visit scheduled
If your insurer has already set an inspection date, it helps to have a roofer's photos and estimate ready beforehand.
Typical cost in Long Beach
What roof insurance claim help usually costs
inspection and documentation $185 to $385
- Size of the roof and of the damaged area
- Roof type and how many sections were affected
- Whether emergency tarping is needed on the same visit
- Attending the adjuster's inspection at the house
- Detail needed in the repair estimate
Repair costs are separate and depend on the damage; the real number comes after we look at your roof. See every price range.
Storm and wind damage claims in Long Beach
Long Beach does not get much weather most of the year, which is part of why storm damage catches people off guard. The usual culprits are winter atmospheric-river storms that bring several days of heavy rain, and fall and winter Santa Ana winds that gust hard across the basin. Wind lifts shingle tabs on ranch homes in Los Altos and North Long Beach, shifts ridge tile on Spanish homes in Bixby Knolls and California Heights, and drops palm fronds and eucalyptus limbs onto roofs across the city.
Near the water, in Belmont Shore and Naples, wind-driven rain off the ocean pushes water under flashing that would stay dry in calmer storms. Older roofs often reveal their weak spots only during the first big rain of the season, and that is when the line between sudden damage and long-term wear needs the most careful description. We document each roof as we find it, from our Long Beach office on E 1st Street or our La Mirada office for the northern cities.
How the job runs
How our crew handles roof insurance claim help
- 1
Call us first
Call (562) 414-1770, any hour. Tell us what happened and whether water is getting in now.
- 2
Protect the roof
If the roof is open, we tarp or temporarily seal it to prevent more damage while the claim is filed.
- 3
Inspect and document
Our roofer photographs and measures the damage, checks the attic, and notes the likely cause.
- 4
Write the estimate
We prepare a plain repair estimate with materials, labor and scope that you can send to your insurer.
- 5
Adjuster walk and repair
If you want, we meet the adjuster on site. Once you decide to move ahead, our crew completes the repair.
FAQ
Roof Insurance Claim Help questions
Will my insurance claim for roof damage be approved if you document it?
We cannot promise that, and no roofer honestly can. Approval depends on your policy and your insurer's review. What our documentation does is give them a clear, accurate record of the damage and a realistic repair estimate.
Should I call my insurer or a roofer first after storm damage?
If water is coming in, call a roofer first so the roof can be tarped. Then contact your insurer to open the claim. Having our photos and estimate ready can make the adjuster visit go more smoothly.
Do you act as my public adjuster on a roof insurance claim?
No. We are your roofing company. We document damage, write the repair estimate and can explain the roof to your adjuster, but we do not negotiate your settlement or represent you in the claim.
Does homeowner insurance cover an old roof that leaks in heavy rain?
Many policies exclude wear, age and maintenance issues, so a leak from failing underlayment on an old tile roof may not qualify. A sudden event such as wind lifting shingles is treated differently. Your policy language and your insurer decide, and our inspection helps show which situation you are in.
Can you tarp the roof before the insurance adjuster comes out?
Yes, and most policies expect you to prevent further damage. We photograph the damage first, then secure a tarp over it. Keep the receipt for the tarping, since it is part of your record.
Where we do this work
Roof Insurance Claim Help around Long Beach
Our crews do this work across Long Beach and the cities around it. A few of the places we cover:
A leak, a quote, or a question about your roof?
Call Denco at (562) 414-1770. Someone answers 24 hours a day, and our crews work out of Long Beach and La Mirada.